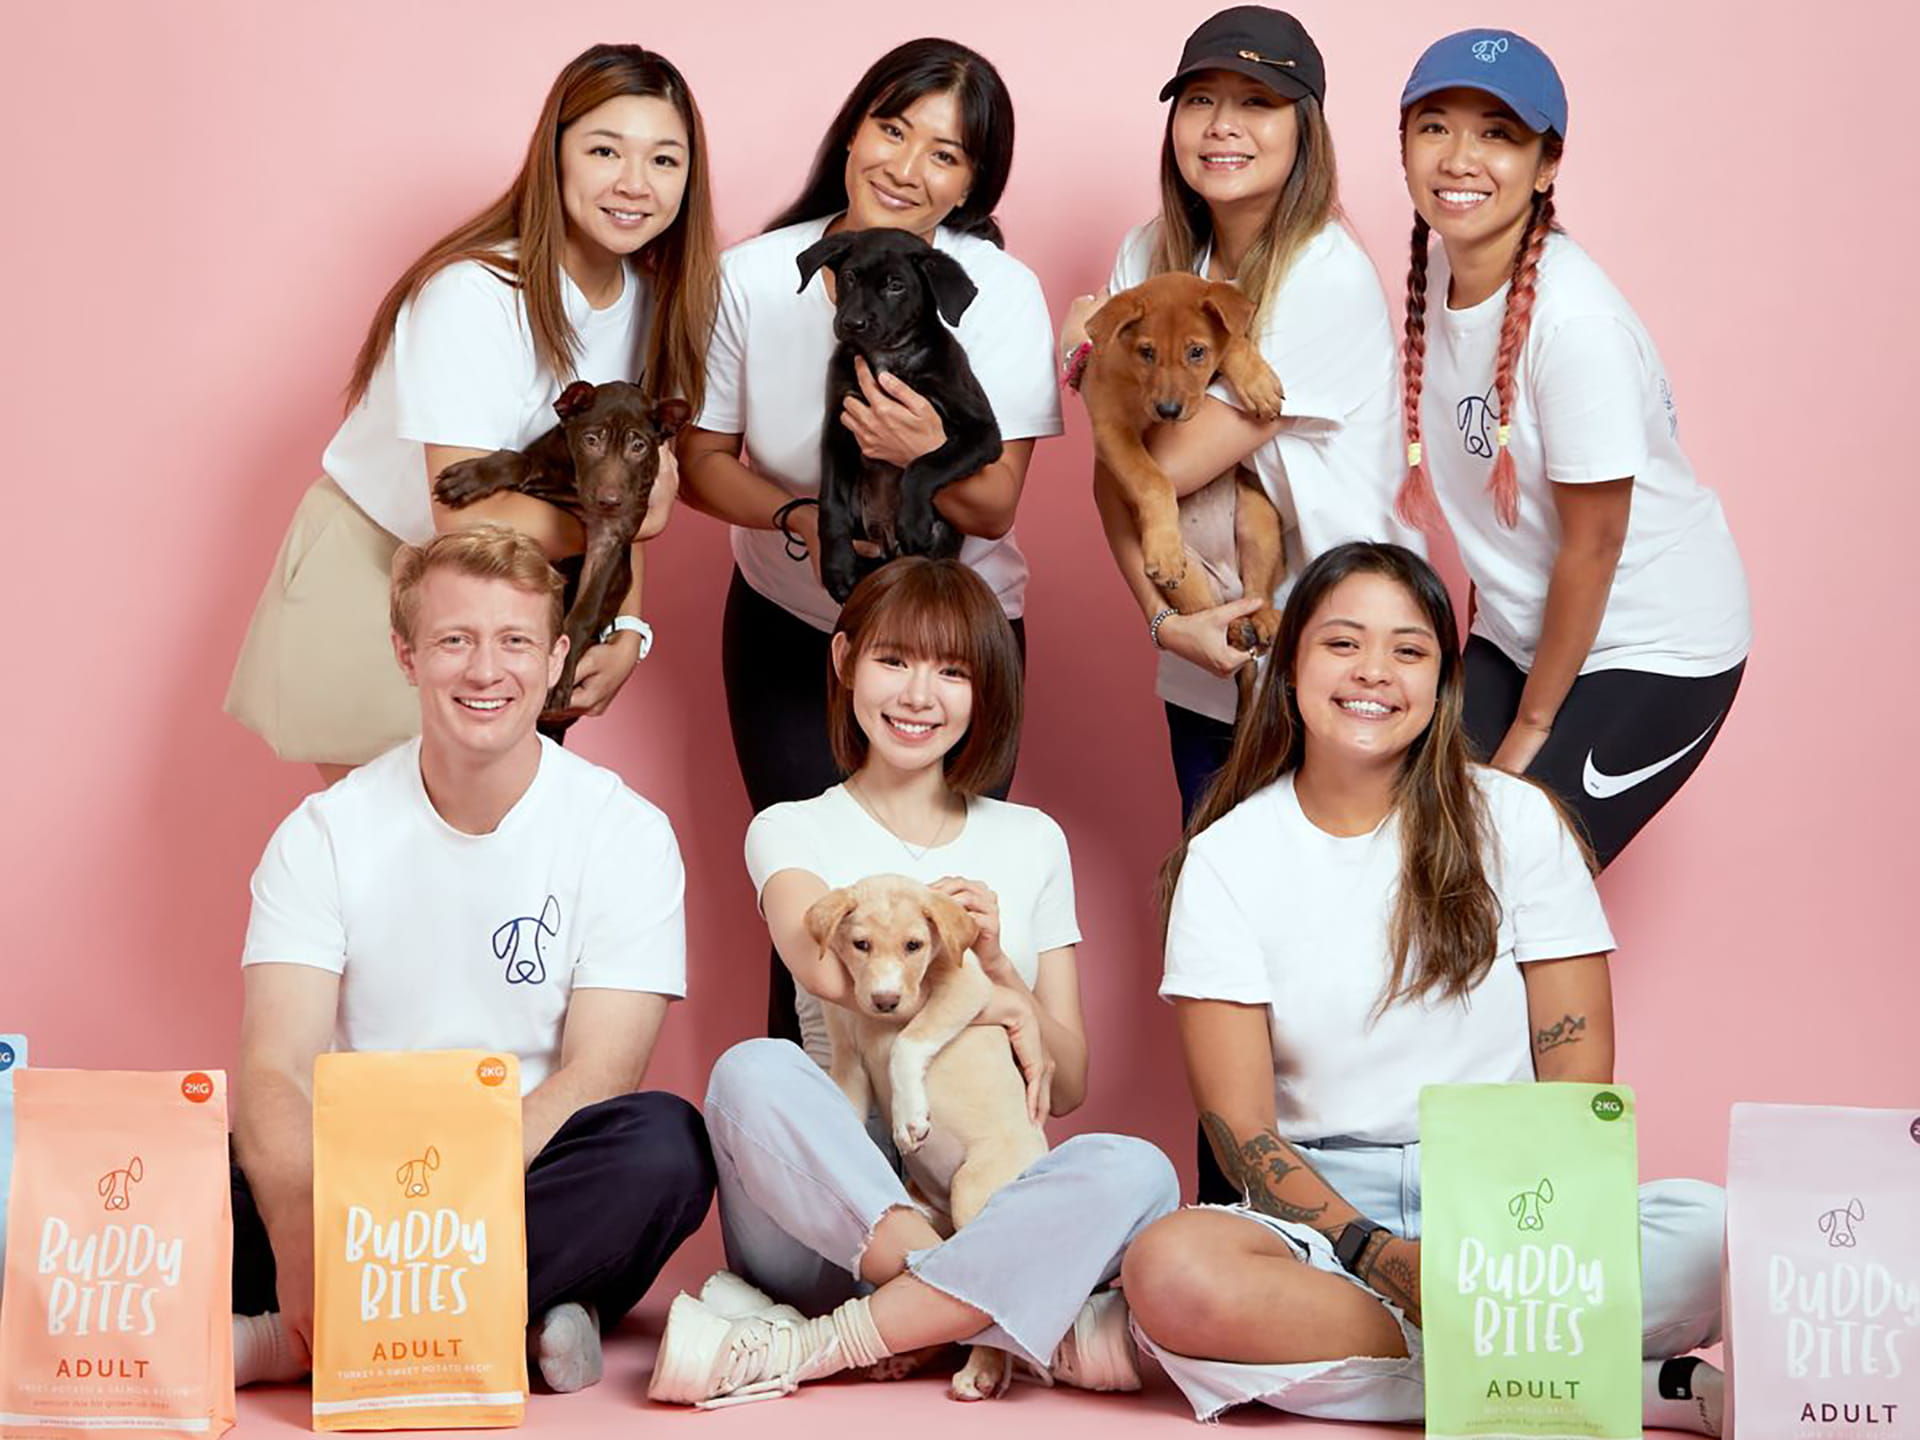
The specific composition of the deal flow this week is worth reading carefully because it contains three separate signals that shape the Malaysian operating environment over the next twelve to twenty-four months. The first signal is the specific Buddy Bites Series A funding. Buddy Bites, founded in 2020 by Ryan Black and Chris Lee, is a Hong Kong-founded pet food company operating through a subscription-led model in Hong Kong and Singapore. The company has now raised USD 4.2 million in Series A funding led by Digitalis Ventures, with participation from Hong Kong venture investor Adrian Lai. That deal marks the company's first institutional venture funding since founding, and it validates the specific commercial model (subscription-based pet food with strong brand-driven positioning) that similar operators are attempting to build across other Asian markets. The company plans to use the funding to expand its core dog food business, grow its shelter donation programme, and develop additional product categories including cat food (launched in June) and shelf-stable fresh dog food (planned for later this year). Buddy Bites will also enter Taiwan as it expands its regional pet nutrition business. The specific implication for Malaysian pet product operators is that the subscription-based direct-to-consumer pet food model is now attracting institutional venture funding across the region, which changes the competitive dynamic for Malaysian operators still operating primarily through traditional retail channels.
The second signal is Kembangan Capital Partners closing USD 725 million across two Asia-focused investment vehicles. Singapore-based KCP, founded by former Temasek executive Koh Wai Kit, invests across private equity and venture capital. The two vehicles will target opportunities in China, India, Japan, South Korea, and Southeast Asia, with focus on artificial intelligence and related infrastructure, healthcare and life sciences, consumer, and financial services. Of the USD 725 million, USD 500 million is allocated to fund-of-funds investments and USD 225 million to direct and co-investments. The specific detail worth reading precisely is that an unnamed sovereign wealth fund investor anchored the round. Sovereign wealth capital returning to fund Southeast Asian private equity is the specific signal that regional sovereign investors (whose specific commitments have been reduced through the 2023 to 2025 period) are moving back into private equity and venture allocations. That specific reallocation has significant implications for the Malaysian private equity market, because sovereign anchor capital typically flows through several downstream general partners before reaching individual portfolio companies.
The third signal is Chandra Asri Pacific's acquisition of Jardine Cycle & Carriage's Singapore and Malaysia automotive businesses. The transaction is structured through Chandra Asri's wholly owned subsidiary CCHPL Holdings, with estimated cash consideration of SGD 265 million (USD 208.6 million) plus an earnout of up to SGD 30 million (USD 23.6 million). Chandra Asri will also assume SGD 333 million (USD 262.1 million) of intra-group loans owed by Jardine Cycle & Carriage to Cycle & Carriage Industries. The transaction covers Cycle & Carriage entities involved in vehicle distribution and retail, used vehicles, aftersales services, financing, and insurance in Singapore and Malaysia, plus associated trademarks and intellectual property used in Singapore, Malaysia, and Myanmar. That specific transaction represents an Indonesian petrochemicals company acquiring a Malaysian and Singaporean automotive retail business, which is the specific type of cross-border strategic acquisition that reshapes the competitive positioning of the domestic Malaysian automotive retail sector. Jardine Cycle & Carriage said the divestment allows it to focus on its core markets of Indonesia and Vietnam, and it will use the sale proceeds to reduce corporate net debt.
The other deals worth flagging briefly include Blackbird closing AUD 1.05 billion (about USD 751 million), described as the largest venture capital raise in Australian and New Zealand history. New investors in the fund include Morgan Stanley Investment Management, Adams Street Partners, and Schroders, joining existing institutional backers including Australia's Future Fund and pension funds Aware Super, HESTA, and Hostplus. Living Roots, a Thailand-based agriculture technology company developing biological alternatives to synthetic fertiliser, raised seed funding from Epic Angels. Neocrete, a New Zealand-based company developing additives for lower-carbon concrete, raised USD 3.5 million in a round led by returning investor Wavemaker Ventures. Craif, a Tokyo-based biotechnology company developing urine-based tests for early disease detection, closed a roughly USD 33 million Series D round co-led by Granite-Integral and Tauns. Tanaka Precious Metal Group invested an undisclosed sum in Tokyo-based Clean Planet, an energy technology company. Each of these represents a specific category position that Malaysian operators in adjacent sectors should be tracking as reference points for regional funding conditions.
The Editor's Note
If you are reading this and the pattern fits your business, start the conversation before the conversation starts itself. editor@unpublished.my.
The China deals worth flagging include Cheng Bai, a Chinese fragrance brand raising an eight-figure RMB pre-Series A from Shanghai Film New Vision Fund. Real Thermal Management Tech, an aerospace-grade thermal management company, raised an eight-figure RMB Series A+ with Innoangel Fund and Jolmo Capital participating. Pandag, a commercial landscaping robotics company, raised an eight-figure RMB Series A from Seas Capital. Tianxing Tansuo, a Beijing-based satellite internet connectivity company, raised an eight-figure RMB angel plus round from Landstone Capital and Plum Ventures. FiveAges, an embodied intelligence company founded in 2024, raised more than RMB 1 billion across consecutive Series A1 and Series A2 rounds with Wuxi High-tech Investment Group, Bank of China's AIC fund, KHK Fund, and others participating. FiveAges' specific plan to prioritise Europe, Australia, New Zealand, Japan, and South Korea for global expansion is the specific type of geographic prioritisation that Malaysian embodied intelligence operators should be studying as they build their own international expansion plans.
The specific N2TP, Graas, and K2 Therapeutics headlines from earlier in the reporting period continue to be relevant reference points. N2TP, a Hanoi-based AI research company, secured seed funding from Touchstone Partners. Graas, a Singapore-headquartered retail AI company, raised USD 17 million in a Series B round led by LemmaTree (a Temasek-founded investment firm) with Integra Partners, Tin Men Capital, The Xander Group, Incred Wealth, and Orzon participating. K2 Therapeutics, a biotechnology company, disclosed USD 50 million in seed financing from MPM BioImpact. Each of these deals represents specific position in the regional venture capital landscape that Malaysian founders in adjacent sectors should be tracking.
For the Malaysian and broader Southeast Asian operator, four implications run from this deals brief.
One. The Malaysian pet product operator should be reading Buddy Bites' regional expansion as a specific competitive threat and a specific commercial opportunity. The subscription-based direct-to-consumer pet food model is now the reference commercial pattern in the category, and Malaysian operators still operating primarily through traditional retail channels face structural competitive disadvantage as Buddy Bites and equivalent operators extend regional distribution. The specific commercial move for Malaysian operators is to evaluate whether their operational infrastructure supports a comparable subscription model, and if not, what specific investments would enable the transition before Buddy Bites extends into the Malaysian market.
Two. The Malaysian sovereign investment vehicle (Khazanah Nasional specifically, along with Employees Provident Fund and Kumpulan Wang Persaraan) should be reading the KCP anchor investment as a signal about the specific pattern regional sovereign allocators are following. If the unnamed sovereign anchor is a regional peer, the specific allocation pattern represents a reference model for how Malaysian sovereign vehicles should be positioning their own regional private equity commitments. If the unnamed sovereign anchor is a non-regional Middle Eastern or European vehicle, the specific allocation represents an opportunity for Malaysian sovereign vehicles to co-invest through the KCP structure and secure exposure to the specific portfolio positions KCP will build.
Three. The Malaysian automotive retail operator (particularly Sime Darby Motors, UMW Toyota, Bermaz Auto, and DRB-Hicom's various dealer network operators) should be reading the Chandra Asri acquisition as a specific competitive positioning shift. Chandra Asri's arrival as a Malaysian and Singaporean automotive retail operator will produce competitive dynamics in the domestic market that did not exist before the transaction. The specific evaluation question for the incumbent Malaysian operators is whether Chandra Asri's Indonesian petrochemicals-linked ownership provides specific competitive advantages (financing terms, cross-selling opportunities with Indonesian consumer product operators, or specific brand positioning) that will materially reshape the Malaysian automotive retail competitive landscape.
Four. The Malaysian venture capital limited partner should be reading Blackbird's AUD 1.05 billion close as a reference data point for how large regional venture funds are now being raised. The specific investor mix (Morgan Stanley, Adams Street, Schroders, Future Fund, and various pension funds) is the specific institutional composition that anchors credible large-fund raises. Malaysian general partners planning larger raises should be building relationships with equivalent institutional investors during the current cycle, before the reference commitment patterns are locked in with competing regional general partners.
The headline is a routine weekly deals brief. The story is the three specific category signals (subscription pet food scaling, sovereign-anchored Asia funds returning, Indonesian petrochemicals entering Malaysian automotive retail) that collectively describe how the Southeast Asian operating environment is quietly restructuring over the current quarter. The Malaysian operator who reads the deals brief as routine news is reading the wrong version. The right version asks which specific competitive positioning decisions each Malaysian operator category needs to be making in response to the specific signals contained in the week's deal flow.